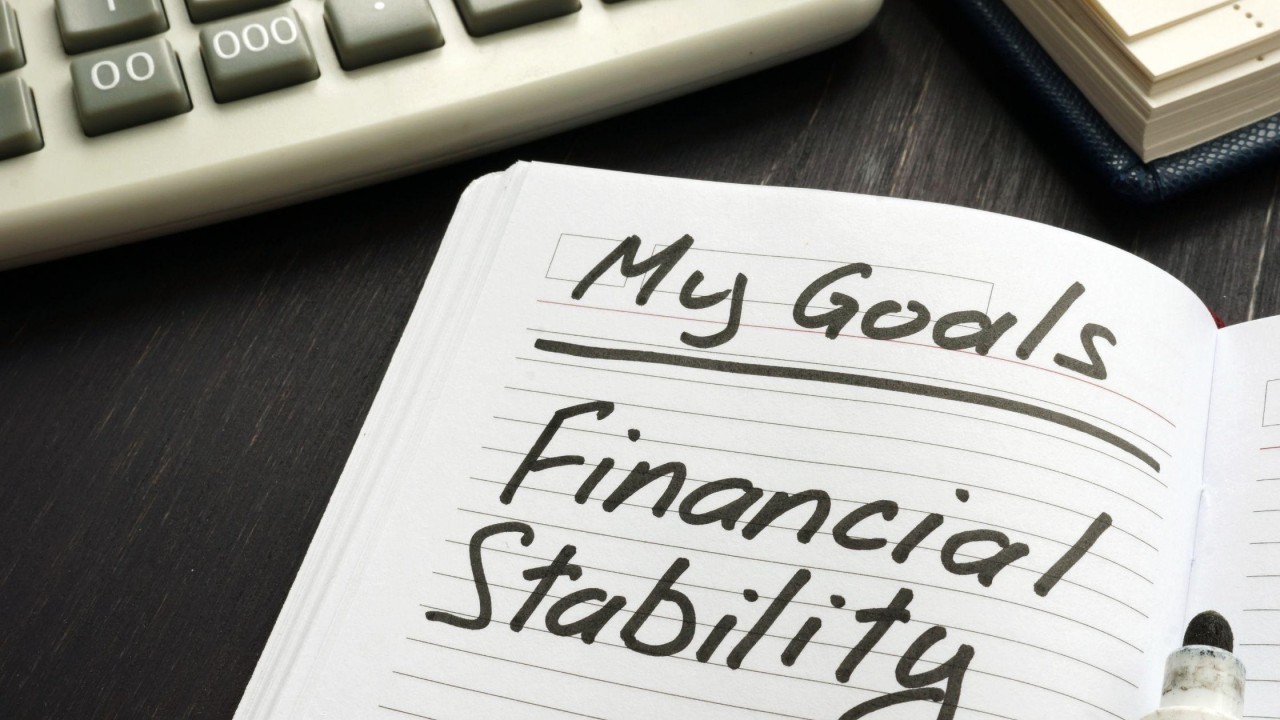
In the context of general Australian finance, financial planning often begins with one key element: setting goals. However, it is not enough to simply think about these goals or vaguely imagine them in the future. Writing them down creates a tangible roadmap that gives structure to decision-making. For many Australians, financial stability is not just about managing money in the present but also about preparing for the future. A written goal becomes an anchor that provides clarity, motivation, and accountability, which are crucial when navigating the complexities of earning, spending, and saving.
While the Australian financial system offers diverse opportunities for growth—such as savings accounts, superannuation, home loans, and managed funds—these options are only truly effective when tied to clear, documented goals. A written plan helps transform abstract ambitions into achievable targets. Whether a couple is saving for their first home in Melbourne, a family is planning for their children’s education in Sydney, or an individual is working toward retirement in Brisbane, the act of documenting financial intentions can serve as a compass through the uncertainties of economic life.
The Psychological Impact of Writing Financial Goals
One of the most overlooked aspects of finance is its psychological component. Writing down financial goals has a powerful effect on the human mind because it externalises what is often an internal desire. Australians who take the step to write their goals often feel more committed to achieving them because they have created a visible contract with themselves. A written goal is no longer fleeting; it becomes a documented reminder that can be revisited, measured, and evaluated.
This psychological commitment can reduce impulsive financial decisions that often undermine long-term success. For example, a young professional saving for a property deposit in Sydney might be tempted to spend excessively on lifestyle experiences. However, by keeping a written reminder of the financial objective, it becomes easier to balance enjoyment today with preparation for tomorrow. The written word reinforces discipline, strengthens accountability, and nurtures perseverance, all of which are crucial in managing general Australian finance effectively.
Linking Written Goals to Broader Financial Planning
General Australian finance is influenced by many moving parts, including taxation policies, interest rates, inflation, and superannuation regulations. Without a structured plan, it is easy to get lost in the noise of these variables. Written goals simplify financial planning by aligning daily financial behaviour with long-term intentions.
For instance, consider a person aiming to retire comfortably at 65. Writing down this goal encourages them to calculate how much they need in their superannuation fund and then adjust their contributions accordingly. It also provides a foundation for conversations with financial advisers, accountants, and other professionals, ensuring that advice received is tailored to specific, documented objectives.
In addition, written goals can serve as benchmarks against which progress can be measured. An Australian household saving for an overseas holiday may review their goal quarterly, making adjustments if their savings rate is falling short. This ongoing process keeps them focused while allowing flexibility when circumstances change. In this way, written goals bridge the gap between broad financial ambitions and the practical realities of daily money management.
Strengthening Household Communication through Written Goals
Finance is rarely a solo journey, especially within households. For Australian couples and families, written goals provide a shared vision that reduces misunderstandings and fosters cooperation. Many disagreements about money arise not because of financial shortage but due to unclear expectations. By writing down goals together, partners ensure they are on the same page.
For example, one partner may prioritise saving for a new car while the other may be more focused on reducing the mortgage. Without written clarity, conflicts may arise. However, by creating a shared document that outlines both priorities and timelines, couples can balance competing interests in a fair and structured way. This approach enhances trust and reduces the emotional strain that often accompanies financial discussions.
Written goals also help teach children about financial responsibility. Parents who set visible family goals, such as saving for a holiday or a home renovation, provide a practical example of planning and discipline. This not only benefits the household financially but also instils valuable habits for the next generation navigating Australia’s financial landscape.
The Connection between Written Goals and Financial Resilience
Australia’s economy, like any other, experiences fluctuations influenced by global markets, natural disasters, and domestic policies. Financial resilience—the ability to withstand and recover from financial shocks—is strengthened when individuals and families have clear written goals. These goals provide a structured framework that helps prioritise spending and saving even during uncertain times.
For instance, a household with a written emergency fund goal will be better prepared when unexpected medical expenses or job losses occur. Instead of resorting to high-interest debt, they can rely on the savings they deliberately built over time. Written goals foster resilience because they embed long-term thinking into financial behaviour, allowing Australians to adapt to challenges without derailing their entire financial plan.
Furthermore, resilience is not only about surviving challenges but also about seizing opportunities. An Australian worker who has written down the goal of advancing their career through education may be more willing to invest in professional courses. When an opportunity arises, their written plan gives them the confidence to act, knowing that such decisions align with long-term aspirations.
Written Goals as a Tool for Accountability
Accountability is one of the greatest benefits of writing down financial goals. Verbal promises can be easily forgotten, but written commitments hold weight. Australians who document their goals can review them regularly and track progress objectively. This level of accountability discourages procrastination and keeps individuals consistent in their actions.
Consider the example of someone aiming to pay off $20,000 of credit card debt within two years. If this goal is written down and broken into smaller monthly targets, accountability becomes measurable. At the end of each month, the individual can assess whether they are on track, behind, or ahead. This system creates transparency, ensuring that progress is visible rather than vague.
Accountability can also extend to professional relationships. Financial advisers often encourage clients to bring written goals to consultations, as it helps shape effective advice. By presenting these goals, clients demonstrate seriousness and invite their advisers to act as accountability partners, further enhancing the likelihood of success.
Overcoming Financial Procrastination with Written Goals
Procrastination is one of the most common barriers to financial progress in Australia. Many people acknowledge the importance of saving, investing, or budgeting, but delay taking meaningful steps. Written goals combat procrastination by transforming intention into action.
When an individual writes down their financial aspirations, they create a sense of urgency and clarity. It is no longer an abstract thought like “I should save more” but a specific, documented target such as “I will save $5,000 by December for a home deposit.” The specificity of a written goal reduces the space for procrastination because it demands action, timelines, and measurable progress.
In the broader context of Australian finance, where the cost of living continues to rise in major cities, procrastination can be particularly damaging. Delaying financial decisions often means higher debt, missed investment opportunities, and slower progress toward homeownership or retirement. Written goals provide a simple yet effective way to break this cycle and instil proactive behaviour.
Flexibility and Adaptation in Written Financial Goals
While the importance of written goals cannot be overstated, it is equally vital to recognise the need for flexibility. Life in Australia, as elsewhere, is unpredictable. Employment changes, health issues, and market fluctuations can disrupt even the best-laid financial plans. Written goals should not be rigid constraints but adaptable guidelines that evolve with circumstances.
For example, a family might initially write down a goal to save for private school fees but later adjust their priorities after reassessing their financial situation. Similarly, an individual saving for a property in Sydney may decide to consider opportunities in more affordable regions after reviewing their budget. The written document provides structure, but it also allows for informed modifications when reality changes.
Flexibility ensures that financial planning remains relevant and realistic. The act of writing goals does not lock Australians into fixed decisions but rather encourages them to approach finance with intention while staying adaptable.
The Broader Cultural and Economic Context of Written Goals in Australia
Australia’s financial culture is shaped by its unique blend of high property values, compulsory superannuation, and a lifestyle that often prioritises experiences such as travel and leisure. In this environment, written financial goals take on added significance. They help Australians navigate the tension between enjoying life in the present and securing long-term stability.
For many, the dream of homeownership remains central to financial planning. Documenting this goal ensures that daily financial habits, such as reducing discretionary spending, align with this ambition. Similarly, written retirement goals help Australians take full advantage of the superannuation system by setting clear contribution targets.
On a cultural level, Australians often value independence and self-reliance. Written goals support these values by empowering individuals to take control of their financial journeys. By committing their ambitions to paper, Australians reinforce the idea that they are responsible for shaping their financial future, rather than leaving it to chance.